Cable and fiber broadband providers’ investment cycle to peak in 2028
Driven by ongoing DOCSIS 4.0 and fiber expansion by cable and fiber providers, the broadband equipment community is set to benefit from a three-year spending cycle.
Dell’Oro Group forecasts that the Broadband Access Equipment market will grow at an average annual rate of 0.5 percent from 2026 to 2030.
Despite the market potential, Jeff Heynen, Vice President at Dell'Oro Group, cautioned that component shortages are driving increases in customer premises equipment costs that could interrupt expansion plans.
Increasing bill-of-materials (BOM) costs for residential Customer Premises Equipment (CPE)—such as advanced fiber and cable gateways—are driving component cost inflation and widening the gap between homes passed by broadband infrastructure and homes connected.
"Large-scale DOCSIS 4.0 and XGS-PON upgrade and expansion projects are well underway, though the increasing bill-of-materials costs for residential CPE threaten to grow gaps in homes further passed and connected," said Jeff Heynen, Vice President of Broadband Access and Home Networking market research at Dell’Oro Group.
XGS-PON deployments accelerate
Led by Tier 1 players AT&T and Verizon, both of which are aggressively expanding their fiber networks through a mixture of organic growth and targeted acquisitions, XGS-PON deployments continue to accelerate.
AT&T and Verizon have set a high bar for fiber broadband deployments.
Having added over 1 million fiber locations in the second quarter, AT&T plans to build 8 million new fiber locations this year, including 4 million from the Lumen acquisition. It is also targeting 40 million by 2026 and 60 million by 2030.
Fellow ILEC Verizon, which completed its acquisition of Frontier earlier this year, has set a goal to expand not only its fiber footprint within and outside of its traditional wireline footprint.
After announcing an agreement with Eaton Fiber last October, Eaton Fiber secured a $1.5 billion investment, supported by the acquisition of Ripple Fiber, bringing Verizon fiber broadband to over a million locations outside its current fiber footprint.
T-Mobile is forming a 50/50 joint venture with Oak Hill Capital to acquire a 50% stake in GoNetspeed and Greenlight Networks. This $2 billion investment expands T-Mobile's high-speed fiber footprint (branded as T-Fiber) across the Northeast and other regional markets.
Based on these aggressive rollout schedules, Dell’Oro forecasts that PON equipment revenue is expected to grow at an average annual rate of 1.6 percent from 2026 to 2030, driven largely by XGS-PON deployments in North America, EMEA, and CALA, as well as FTTR (Fiber to the Room) deployments in China.
“XGS-PON is really ramping up—especially in North America, where it has already surpassed GPON in terms of new OLT ports and ONTs,” Heynen said. “The fact that many fiber ISPs still have to contend with cable operators who are doing mid- and high-split DOCSIS 3.1 and DOCSIS 4.0 upgrades means they will have to deploy multi-gigabit fiber services. The only way to do that now is with XGS-PON.”
Likewise, Tier 2 and remaining competitive players (which are also being acquired) are also moving along with their XGS-PON paths.
“It’s pretty clear that those operators are moving forward with XGS-PON right now,” Heynen said. “Calix, Adtran, and Nokia have already seen significant shifts to XGS-PON from their tier 2 customer base.”
In Europe, Tier 1 telcos are only now switching to XGS-PON, while European cable competitors are staying at DOCSIS 3.1 with mid- and high-splits.
Heynen noted that “residential ARPU is considerably lower in most countries, which means it takes longer to recoup your investment in more expensive technologies.”
Cable’s DOCSIS 4.0, fiber momentum
As cable operators move toward DOCSIS 4.0 and fiber deployments, suppliers will benefit from these spending patterns.
In 2026, Dell’Oro expects Cable Outside Plant Equipment revenues to increase 20 percent year-over-year (Y/Y), mainly due to accelerated deployment of new 1.8 GHz amplifiers and new DAA and GAP (Generic Access Platform) Nodes to support Remote PHY and Remote OLT deployments.
Revenue for Cable Distributed Access Equipment (Virtual CCAP, Remote PHY Devices, Remote MACPHY Devices, and Remote OLTs) “is expected to peak in 2028 and 2029, as operators continue their DOCSIS 4.0 and early fiber deployments.”
From a geographic point of view, North America will lead spending on Cable Outside Plant Equipment revenue, as cable operators in other regions move ahead with either DOCSIS 3.1 or overbuilding HFC networks with fiber.
The research firm expects Global Cable Outside Plant Equipment revenues to peak in 2027, when the largest number of tier one operators in North America are expected to be in the middle of their amplifier, node, and passives upgrades for mid- and high-split DOCSIS 3.1 and DOCSIS 4.0 service deployment.
The market will continue to grow, peaking in 2027, as operators add more capacity and resilience through smart amplifiers and nodes.
Tier 1 cable operators, including Comcast and Charter, are moving fast with their DOCSIS 3.1 mid- and high-split and DOCSIS 4.0 deployments. Similarly, Cable One and Mediacom are moving along this path as well, with more of a mix of technologies depending on their systems.
“It’s important to note that most cable operators generally replace 2% of their coax networks with fiber just due to age,” Heynen said. “So, some overbuilding is happening in addition to the greenfield buildouts.”
Another key segment within the cable industry that is being aggressive are smaller cable overbuilders like Astound Broadband (merging with GFiber) and WOW, which went private earlier this year.
Since it was purchased by DigitalBridge Group and Crestview Partners in January, WOW has announced fiber broadband builds in Southeastern Alabama, East Central Michigan, South Carolina and Central Florida.
The market will continue to increase, peaking in 2027, as operators continue to add more capacity and resilience through smart amplifiers and nodes.
One of the benefits of this deployment cycle is that providers will have more visibility into network performance. Nearly 10 million of the new amplifiers expected to be deployed during this cycle will have transponders or DOCSIS modems onboard to improve fault detection and resolution capabilities dramatically.
“2025 was the first of a four-year spending cycle to boost broadband speeds, while also dramatically improving the reliability and PNM (Proactive Network Maintenance) capabilities of their outside plant,” said Heynen. “These upgrades will result in a significant increase in spending on optical nodes, amplifiers, and passive equipment, including taps and hardline splitters, through 2028.”
Considering Wi-Fi 7 options
Wi-Fi 7, the latest Wi-Fi flavor, will continue to have a presence in the broadband space as service providers roll out enhanced network speeds for consumers and businesses.
Already, Tier 1 broadband providers, including Spectrum, Comcast Xfinity, AT&T, and Fidium Fiber, are rolling out Wi-Fi 7 routers and multi-gigabit speed tiers to handle dense smart homes and high-bandwidth applications.
But service providers’ adoption of Wi-Fi is not just about speed alone. It is also about offering premium features. Spectrum offers consumers an advanced Wi-Fi 7 router and "Invincible WiFi," which pairs Wi-Fi 7 with an integrated battery and 5G cellular backup for continuous connection during a power outage.
Likewise, regional competitors like Archtop Fiber and Fidium are also offering Wi-Fi 7 capabilities as part of their 5 and 8 Gbps broadband packages, leveraging eero’s platform.
Heynen said the research firm is seeing broadband providers offer Wi-Fi 7 at multiple levels.
“It isn’t just a premium add-on; it is also becoming more of a standard add-on,” he said. “The premium tiers get full tri-band (2.4, 5, 6 GHz) Wi-Fi 7, while the standard tiers get dual-band (2.4, 5 GHz) Wi-Fi 7.”
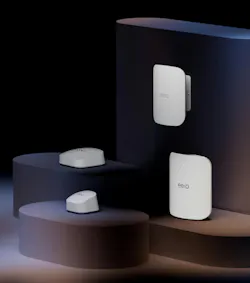
He added, “ISPs that are partnering with eero offer the eero 7 Max as their premium add-on and the eero 7 as the standard add-on.”
Dell’Oro noted that while there will be lower total unit shipments of Wi-Fi 7 platforms due to higher expected Average Selling Prices (ASPs), Wi-Fi 7 residential routers and broadband CPE with WLAN will grow steadily through 2030.
Heynen said that ISPs are combating higher manufacturing costs through cutting how much premium Wi-Fi equipment they buy and increasing investments in device reuse and refurbishing programs to extend the lifespan of older CPE.
“We are already seeing CPE vendors pass along the additional costs to their ISP end customers. Not a 100% pass-through but certainly a percentage,” he said. “As for ISPs, they are going to reduce their purchases of new units and look to refurbish units that customers return. That said, many ISPs just leave the ONT in place once it’s either in the house or on the side of the house. So, refurbishing can only take them so far.”
For related articles, visit the FTTx Topic Center.
For more information on FTTx technology and suppliers, visit the Lightwave Buyer’s Guide.
To stay abreast of fiber network deployments, subscribe to Lightwave’s Service Providers and Datacom/Data Center newsletters.
*This article was updated with additional information from Dell'Oro Group.
About the Author
 Sean Buckley
Sean is the Editor-in-Chief of Lightwave. He establishes and executes Lightwave's editorial strategy across its website, email newsletters, events, and other information products. Before coming to Lightwave in July 2023, he served as editor of Broadband Communities. Earlier, he served as senior editor of FierceTelecom and the editor of the former Telecommunications Magazine. He got his start in the optical industry in 1998 when he became the editor of enterprise and optical networks at Information Gatekeepers. He has a BA in English from the University of Massachusetts, Boston, and lives in Dracut, Mass, with his wife, two sons, and his cat, Dove.